Phone
Phone
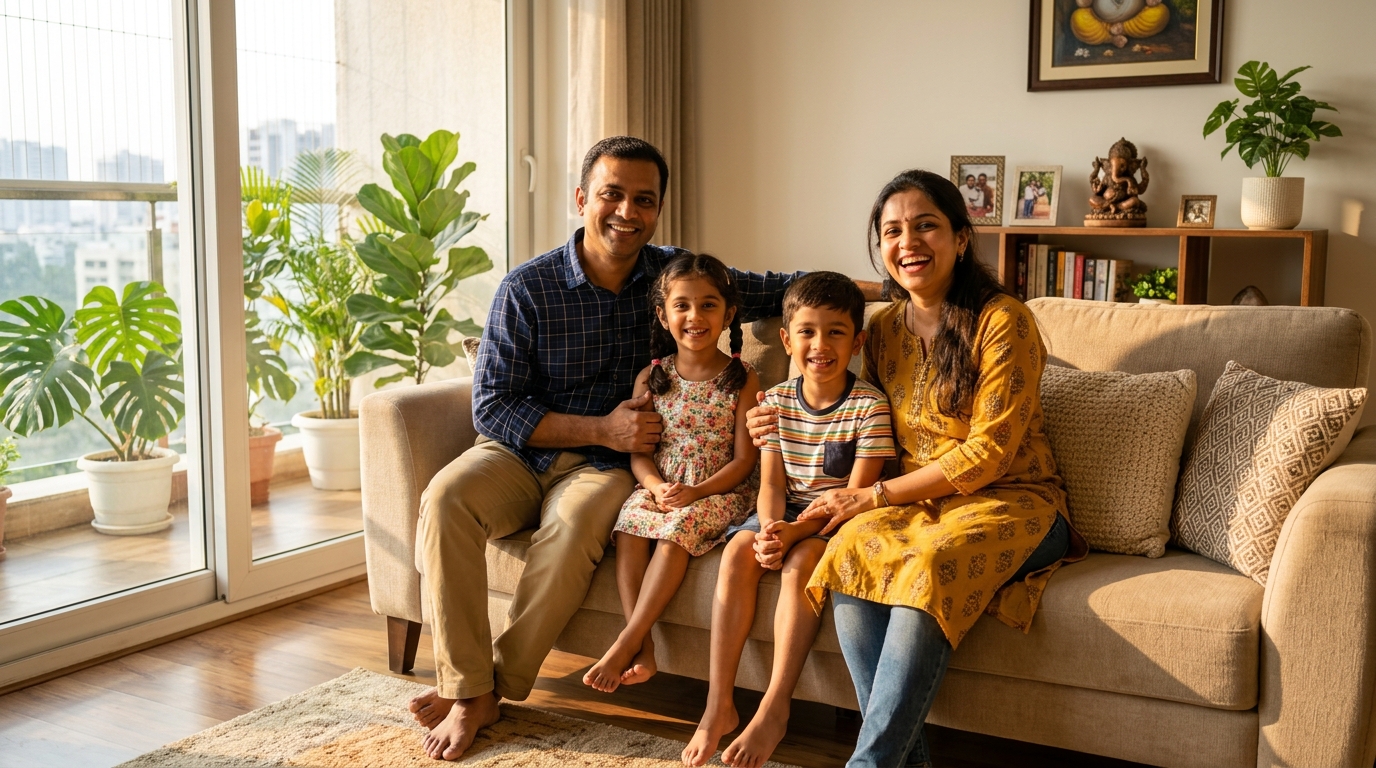
A Family Floater health insurance policy covers all family members under a single shared sum insured, saving up to 45% on annual premiums compared to separate individual policies. However, for senior parents above 60 with pre-existing conditions, dedicated individual policies remain essential to prevent high claim frequency from depleting the family pool.
Choosing between an Individual Health Insurance policy and a Family Floater plan is one of the most critical financial choices a family makes. A family floater plan allows spouse and dependent children to float over one central sum insured. But how do you calculate when a floater plan stops being cost-effective? In this analysis, BimaSpot provides the exact decision framework to protect your family while optimizing premium expense.
Family floater policies are the ideal choice when all members are young, healthy, and below the age of 45. In a typical young nuclear family consisting of parents (aged 32 and 30) and two kids (aged 5 and 2), the statistical probability of simultaneous hospitalizations in a single policy year is under 0.2%. A shared sum insured of ₹15 Lakhs or ₹25 Lakhs gives ample financial breathing room while keeping the annual premium under ₹18,000.
| Family Composition | 4 Individual Policies | 1 Family Floater (₹15L) | Estimated Annual Savings |
|---|---|---|---|
| Self (32) + Spouse (30) | ₹16,500 / year | ₹11,800 / year | ₹4,700 (28% Saved) |
| Self (35) + Spouse (33) + 2 Children | ₹34,200 / year | ₹21,400 / year | ₹12,800 (37% Saved) |
| Self + Spouse + Parents (62) | ₹58,000 / year | ₹52,000 / year | Not Recommended (Keep Parents Separate) |
Under Section 80D of the Income Tax Act, purchasing health insurance for your family yields substantial tax savings. You can claim up to ₹25,000 for yourself, your spouse, and dependent children. If you also pay premiums for your parents who are senior citizens (above 60 years), you can claim an additional deduction of up to ₹50,000. For families where both the taxpayer and parents are senior citizens, total tax exemptions reach an impressive ₹1,00,000 annually. In addition, preventive health check-up costs up to ₹5,000 per financial year can be claimed within these overall thresholds.
As parents cross the age of 55 or 60, their risk of chronic lifestyle ailments such as diabetes, hypertension, and cardiovascular disorders increases. If parents remain in a family floater policy with children, the premium is calculated according to the eldest member's age, dramatically inflating the entire family's premium. Moreover, any claim by parents wipes out the accumulated No-Claim Bonus (NCB) of the entire family. Therefore, BimaSpot recommends porting senior parents into an independent Senior Citizen Health Policy while retaining a cost-effective floater for the young nuclear unit.
At BimaSpot, our advisors advocate the Hybrid Coverage Formula. Instead of buying an expensive ₹1 Crore base policy, combine a ₹15 Lakhs base family floater plan with a ₹50 Lakhs Super Top-Up policy (with a ₹15 Lakhs deductible). This reduces total family health premiums by up to 55% while securing an invincible ₹65 Lakhs healthcare umbrella.
Speak directly with BimaSpot's senior health advisors. We calculate the exact premium sweet spot for your family.
Get WhatsApp Recommendation
Copyright © 2026, bimaspot.com . All Rights Reserved.